BDC resubmission · September 2026
10-year pro forma
Consolidated, all three parcels. Rents +2%/yr, expenses +3%/yr, CHAP credit for 10 years, exit at a 8.0% cap.
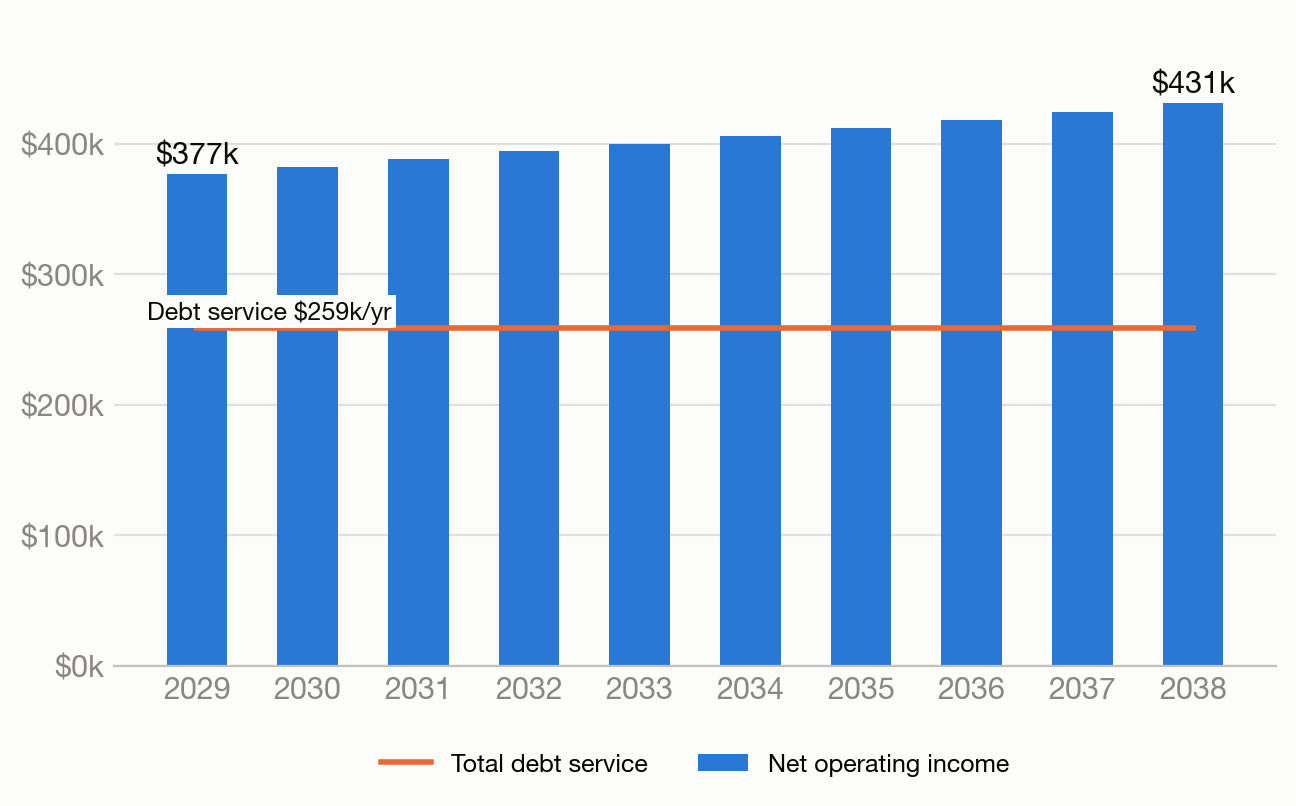
| 2029 | 2030 | 2031 | 2032 | 2033 | 2034 | 2035 | 2036 | 2037 | 2038 | |
|---|---|---|---|---|---|---|---|---|---|---|
| Effective gross income | $579,936 | $591,535 | $603,365 | $615,433 | $627,741 | $640,296 | $653,102 | $666,164 | $679,487 | $693,077 |
| Operating expenses (net of CHAP) | $203,434 | $209,247 | $215,229 | $221,384 | $227,718 | $234,235 | $240,942 | $247,844 | $254,946 | $262,255 |
| Net operating income | $376,502 | $382,288 | $388,137 | $394,049 | $400,024 | $406,061 | $412,160 | $418,320 | $424,541 | $430,822 |
| NIIF debt service | $191,091 | $191,091 | $191,091 | $191,091 | $191,091 | $191,091 | $191,091 | $191,091 | $191,091 | $191,091 |
| 1816 debt service | $67,831 | $67,831 | $67,831 | $67,831 | $67,831 | $67,831 | $67,831 | $67,831 | $67,831 | $67,831 |
| Total debt service | $258,922 | $258,922 | $258,922 | $258,922 | $258,922 | $258,922 | $258,922 | $258,922 | $258,922 | $258,922 |
| DSCR | 1.45x | 1.48x | 1.50x | 1.52x | 1.54x | 1.57x | 1.59x | 1.62x | 1.64x | 1.66x |
| Cash flow after debt service | $117,580 | $123,365 | $129,215 | $135,127 | $141,102 | $147,139 | $153,238 | $159,398 | $165,619 | $171,900 |
| Deferred developer fee paid | $58,790 | $61,683 | $64,607 | $37,069 | $0 | $0 | $0 | $0 | $0 | $0 |
| Distributable cash flow | $58,790 | $61,683 | $64,607 | $98,058 | $141,102 | $147,139 | $153,238 | $159,398 | $165,619 | $171,900 |
Returns
| Measure | Value |
|---|---|
| Levered IRR (sponsor, 10-yr) | 11.6% |
| Unlevered IRR (project) | 0.6% |
| Return on cost (Yr 1 NOI ÷ TDC) | 4.6% |
| Average cash-on-cash | 10.7% |
| Equity multiple | 2.16x |
| Gross sale value (Yr 11 NOI ÷ exit cap) | $4,732,893 |
| Loan balances at Yr 10 (NIIF + 1816) | $2,632,921 |
| Net reversion to sponsor (after BDC repayment) | $1,014,112 |